


Page 31
P. 31
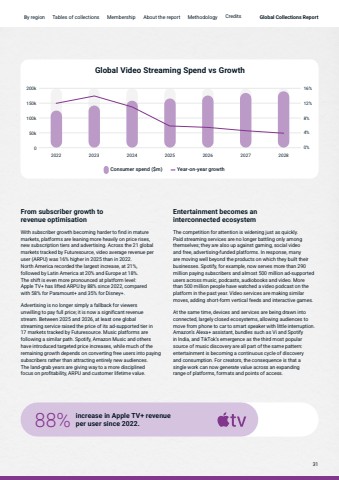
From subscriber growth to revenue optimisationWith subscriber growth becoming harder to find in mature markets, platforms are leaning more heavily on price rises, new subscription tiers and advertising. Across the 21 global markets tracked by Futuresource, video average revenue per user (ARPU) was 16% higher in 2025 than in 2022. North America recorded the largest increase, at 21%, followed by Latin America at 20% and Europe at 18%. The shift is even more pronounced at platform level: Apple TV+ has lifted ARPU by 88% since 2022, compared with 58% for Paramount+ and 35% for Disney+.Advertising is no longer simply a fallback for viewers unwilling to pay full price; it is now a significant revenue stream. Between 2025 and 2026, at least one global streaming service raised the price of its ad-supported tier in 17 markets tracked by Futuresource. Music platforms are following a similar path. Spotify, Amazon Music and others have introduced targeted price increases, while much of the remaining growth depends on converting free users into paying subscribers rather than attracting entirely new audiences. The land-grab years are giving way to a more disciplined focus on profitability, ARPU and customer lifetime value.Entertainment becomes an interconnected ecosystemThe competition for attention is widening just as quickly. Paid streaming services are no longer battling only among themselves; they are also up against gaming, social video and free, advertising-funded platforms. In response, many are moving well beyond the products on which they built their businesses. Spotify, for example, now serves more than 290 million paying subscribers and almost 500 million ad-supported users across music, podcasts, audiobooks and video. More than 500 million people have watched a video podcast on the platform in the past year. Video services are making similar moves, adding short-form vertical feeds and interactive games.At the same time, devices and services are being drawn into connected, largely closed ecosystems, allowing audiences to move from phone to car to smart speaker with little interruption. Amazon%u2019s Alexa+ assistant, bundles such as Vi and Spotify in India, and TikTok%u2019s emergence as the third most popular source of music discovery are all part of the same pattern: entertainment is becoming a continuous cycle of discovery and consumption. For creators, the consequence is that a single work can now generate value across an expanding range of platforms, formats and points of access.Global Video Streaming Spend vs Growth2022 2023 2024 2025 2026 2027 20280%4%8%12%16%Consumer spend ($m) Year-on-year growth050k100k200k150k88% increase in Apple TV+ revenue per user since 2022.Global Collections Report31


